First Graphene Stock Price
The public debut of graphene companies marked a dramatic transition for advanced materials science, moving single-atom-thick carbon from academic laboratories onto public equity markets. When investors sought the first graphene stock price, they encountered an asset class defined far more by scientific speculation, patent filings, and pilot-scale synthesis than by mature balance sheets or high-volume industrial revenues. Understanding how early graphene equities were valued requires analyzing the gap between laboratory breakthroughs and commercial manufacturing economics.
The Transition from Laboratory Discovery to Public Equity
Graphene was first isolated by mechanical exfoliation in 2004, an achievement recognized with the Nobel Prize in Physics in 2010. That scientific milestone ignited worldwide commercial interest. Venture capital and private funding initially supported fundamental synthesis research, but the intense capital requirements of nanomaterial scale-up soon drove pioneer enterprises toward public listings.
Early public entries predominantly took place on growth-oriented, junior stock exchanges such as the London Stock Exchange Alternative Investment Market (AIM), the TSX Venture Exchange (TSX-V), and the Australian Securities Exchange (ASX). These exchanges offered pre-revenue deep-tech enterprises access to liquidity while allowing retail and institutional investors direct exposure to early-stage material science.
The initial pricing of these shares rarely reflected standard enterprise multiples, such as price-to-earnings or enterprise-value-to-EBITDA. Instead, listing prices were established via discounted cash flow models driven by speculative adoption curves, nominal production capacities, and the perceived strength of proprietary synthesis patents.
Core Drivers Behind Pioneer Graphene Stock Valuations
When the earliest pure-play graphene entities floated shares, underwriting institutions and market makers structured opening valuations around three primary pillars:
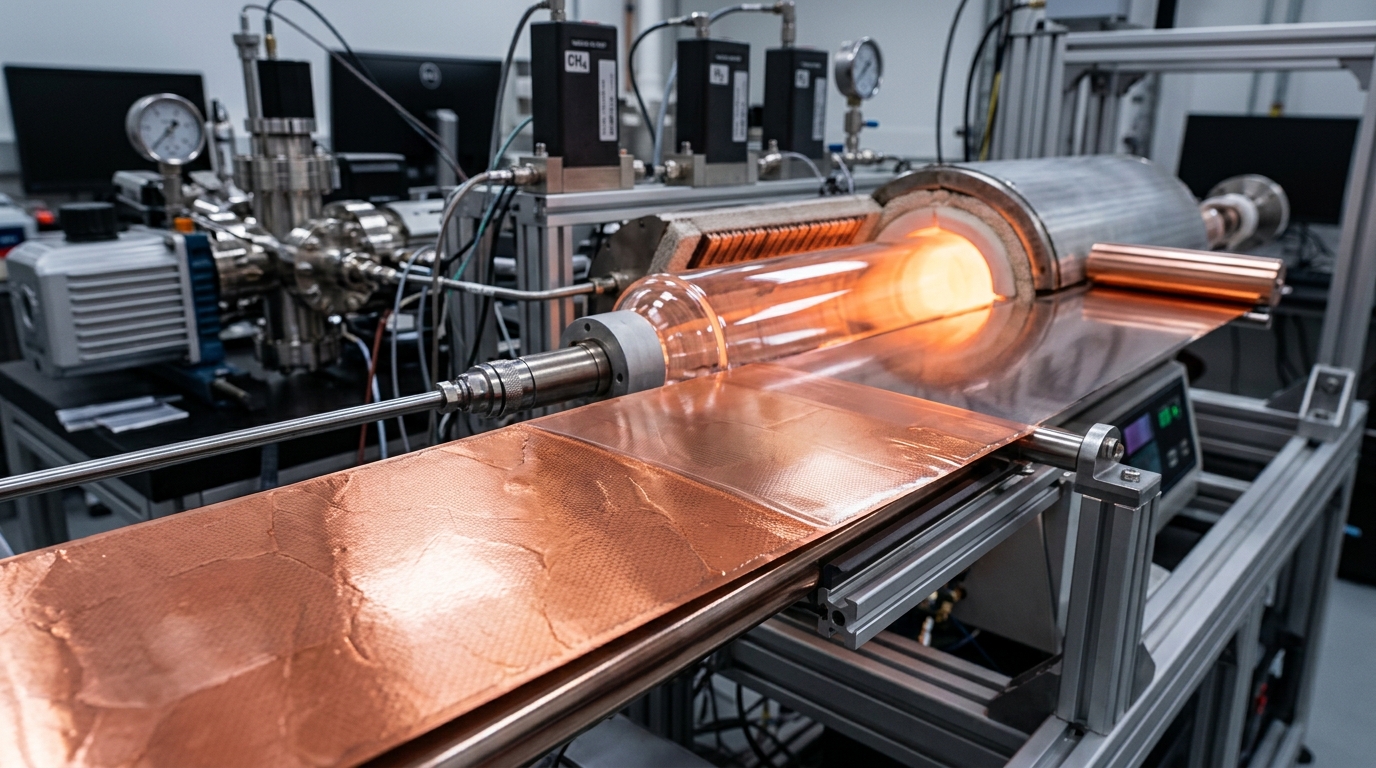
- Synthesis Technology and Intellectual Property: Companies holding exclusive licenses or foundational patents for scalable synthesis commanded significant premiums. Valuation depended heavily on whether an enterprise utilized bottom-up approaches, such as chemical vapor deposition, or top-down methods, such as liquid-phase graphite exfoliation.
- Scale-Up Milestones vs. Laboratory Yields: A fundamental hurdle in 2D materials is the non-linear relationship between producing milligram samples in a research reactor and maintaining multi-ton annual output with uniform defect density. Initial public pricing heavily weighted pilot-plant completion timelines.
- Offtake and Evaluation Agreements: Because baseline sales were minimal, market valuations reacted sharply to non-binding joint development agreements (JDAs) or material evaluation trials with major industrial partners in aerospace, energy storage, or structural composites.
Structural Differences Across Early Listed Material Producers
Not all companies trading under the graphene banner operated the same business model. Market confusion often blurred the lines between different operational structures, directly influencing market capitalization and price volatility.
| Company Classification | Primary Production Mechanism | Target Market Sector | Primary Valuation Driver |
|---|---|---|---|
| Pure-Play CVD Synthesizers | Chemical vapor deposition on metal substrates | Semiconductors, transparent conductors, photonics | Device integration patents and wafer-scale uniformity |
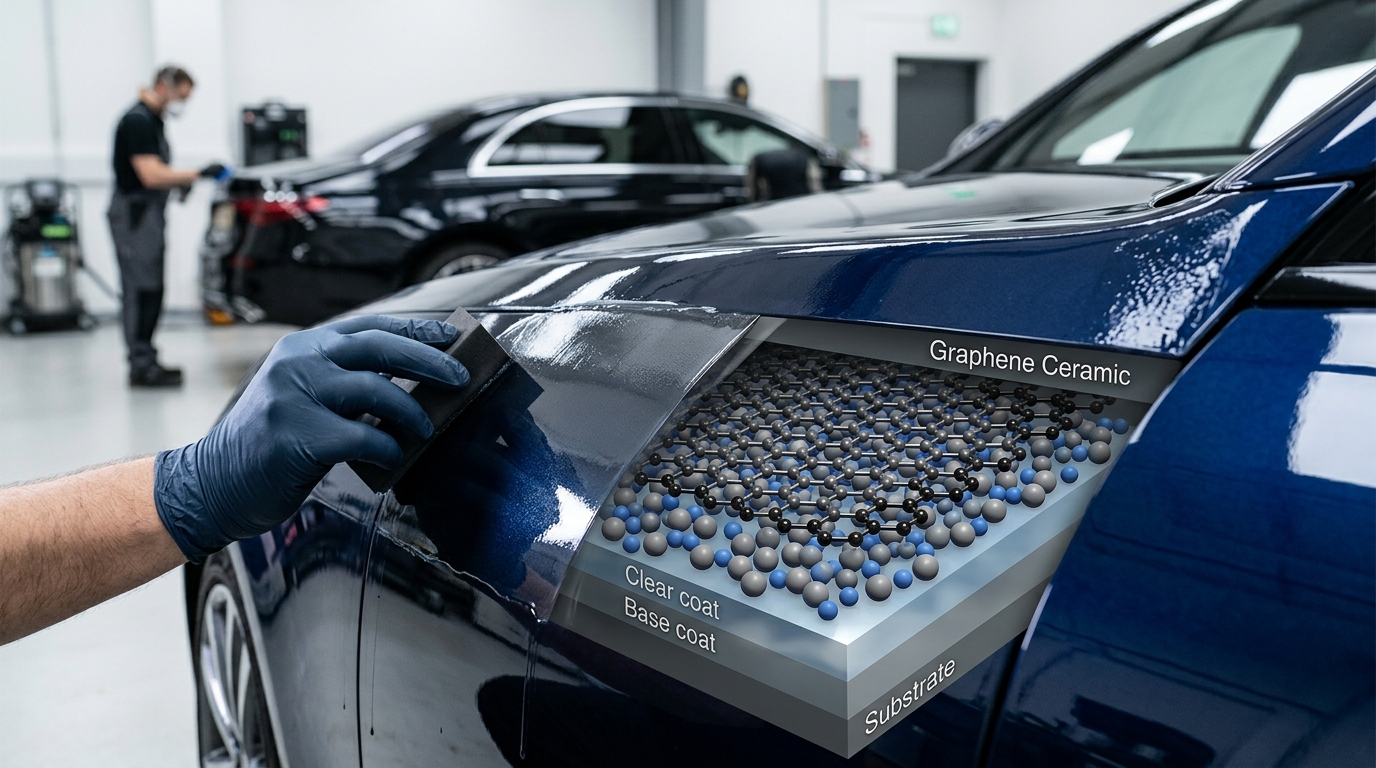
| Bulk Exfoliation Producers | Liquid-phase and chemical reduction methods | Composites, paints, concrete, conductive masterbatches | Per-kilogram processing costs and industrial volume capacity |
| Converted Mining Explorers | Graphite extraction paired with downstream processing | Battery anode materials and basic additives | Resource asset size coupled with proprietary purification claims |
Investors analyzing initial equity prices faced significant divergence between these models. A company synthesizing high-purity monolayer films faced massive engineering barriers in device transfer and semiconductor integration, whereas bulk powder producers faced lower technical hurdles but wrestled with commoditization and customer dispersion issues.
The Material Definition Dilemma in Early Market Pricing
A central challenge surrounding the first publicly traded graphene offerings was the absence of universal international characterization standards. In early market cycles, the term graphene was frequently applied to materials ranging from true single-layer sheets to multi-layer graphene nanoplatelets and even finely milled graphite powders.
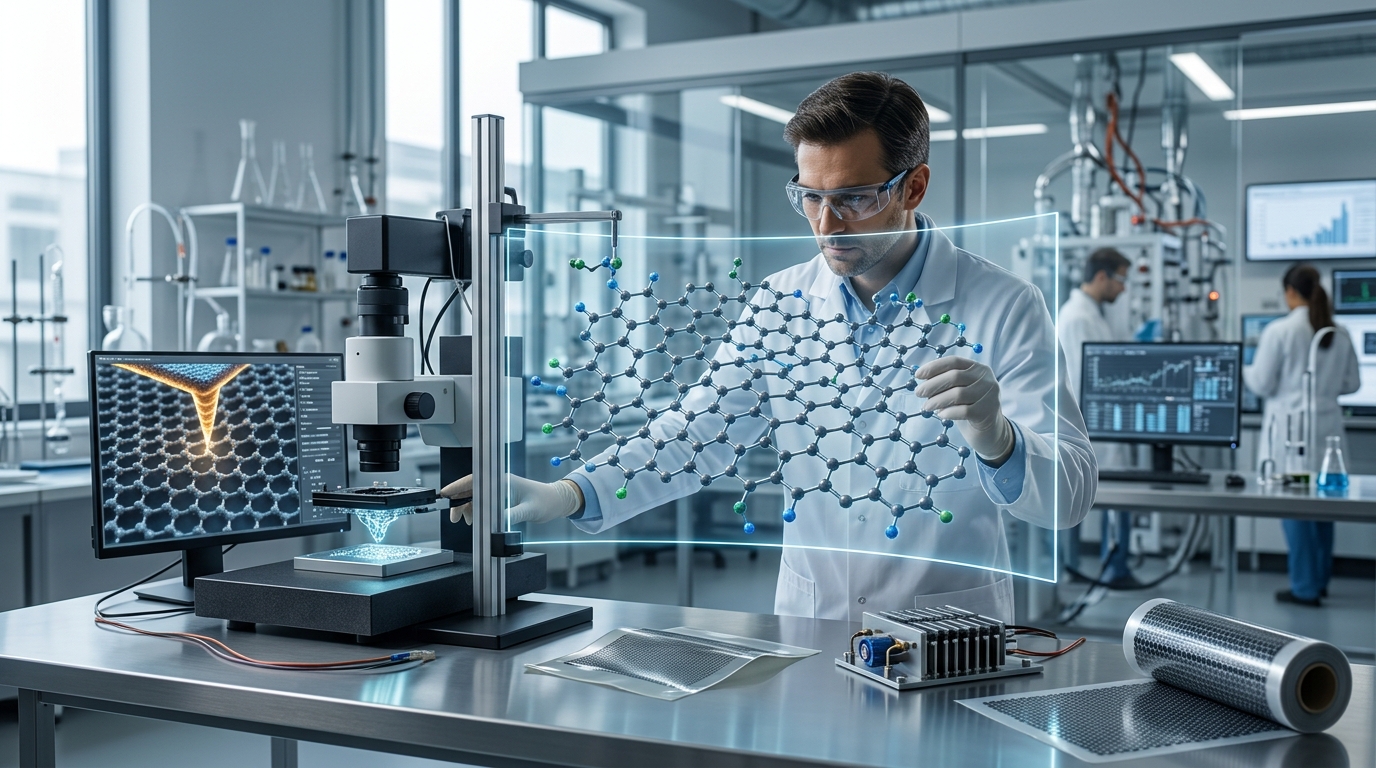
Pristine monolayer graphene consists of a single hexagonal lattice of sp2-bonded carbon atoms exhibiting exceptional charge carrier mobility and theoretical tensile strength. However, bulk industrial applications routinely utilized graphene oxide (GO), reduced graphene oxide (rGO), or nanoplatelets exceeding ten carbon layers in thickness. These thicker variants offered improved mechanical reinforcement in bulk matrices but lacked the electronic properties of pristine monolayers.
Because early equity listings often marketed the theoretical physics of monolayer carbon while selling multi-layer additives, public pricing frequently experienced sharp corrections when enterprise revenue failed to scale at the pace predicted by promotional material descriptions.
Technical and Commercial Bottlenecks That Shaped Share Performance
Once the initial public offering dust settled, early graphene market prices were governed by the physical and logistical realities of material integration.
Matrix Compatibility and Dispersion Chemistry
Graphene sheets possess exceptionally high specific surface areas and strong van der Waals attractions, creating a persistent thermodynamic tendency to agglomerate into graphite-like clusters when added to polymers, resins, or solvents. Overcoming this agglomeration required proprietary surface functionalization chemistry or customized dispersion masterbatches. Pioneer companies that failed to solve dispersion compatibility found that their industrial customers could not replicate laboratory performance gains in factory-floor trials.
Supply Chain Qualification Cycles
Unlike software or consumer technology, introducing an advanced nanomaterial into regulated sectors such as aerospace, automotive structures, or medical equipment requires exhaustive multi-year qualification cycles. Component testing, fatigue analysis, toxicity assessments, and regulatory approvals repeatedly extended commercialization timelines far beyond initial equity market expectations.
Capital Expenditure and Dilution Risk
Building specialized reactors, automated continuous-flow exfoliation lines, and cleanroom handling facilities required substantial capital outlays. Because early commercial revenue remained modest, pioneer public companies frequently relied on secondary share placements, rights issues, and convertible debt. This ongoing equity dilution risk placed downward pressure on per-share prices, establishing a more grounded, valuation-conscious market environment.
Framework for Evaluating Advanced 2D Material Equities
Assessing the fundamental viability of deep-tech materials enterprises requires moving past top-line marketing claims to analyze technical capabilities and manufacturing discipline:
- Material Characterization Rigor: Reliable enterprises validate their product portfolios through recognized analytical techniques, such as Raman spectroscopy ratios (specifically measuring the relative intensity and shape of the D, G, and 2D peaks) alongside transmission electron microscopy (TEM) and atomic force microscopy (AFM) to verify true layer thickness and structural integrity.
- Unit Economics and Yield Consistency: Evaluating enterprise value demands examining the cost per kilogram or cost per square meter at specific production volumes, factoring in precursor materials, energy inputs, and batch-to-batch structural consistency.
- Addressable Problem-Specific Economics: Graphene is not a universal substitute; it provides economic value only where minor additive percentages produce disproportionate performance gains that outweigh the cost of the raw additive and the processing modifications required to blend it.
- Capital Discipline and Runway: Given prolonged development timelines, a sustainable material company requires sufficient balance-sheet liquidity to navigate multi-year industrial testing protocols without excessive equity dilution.
The Legacy of Pioneer Graphene Valuations
The arrival of the earliest publicly traded graphene securities served a vital purpose in the maturation of modern nanotechnology. While initial market valuations reflected early enthusiasm and theoretical performance limits, the subsequent market normalization forced companies to shift focus from academic novelty toward rigorous production engineering, standardized characterization, and reliable supply contracts.
Pioneer stock prices established the benchmark against which modern advanced material commercialization is measured, proving that industrial success in engineered carbon relies not merely on exceptional physics, but on manufacturing scalability, dispersion chemistry, and disciplined unit economics.