Graphene Stocks
Regulatory Notice: This article is published exclusively for informational and educational research purposes and does not constitute financial, investment, legal, or tax advice. Advanced nanomaterials equities involve substantial financial risk, volatility, and liquidity constraints. Mention of specific corporate entities, stock tickers, or exchanges does not constitute a recommendation to buy, sell, or hold any security.
The Graphene Public Equity Landscape
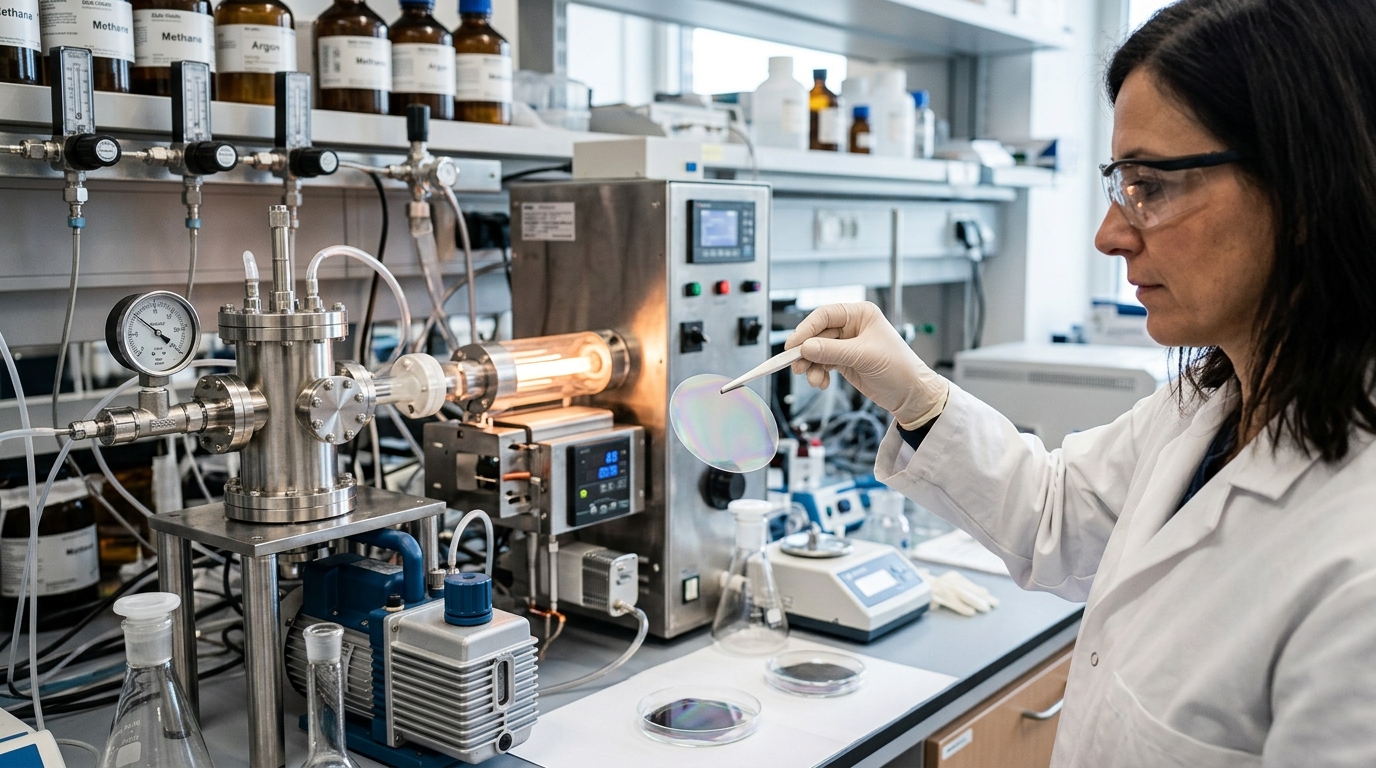
The global commercial graphene sector is transitioning from laboratory-scale synthesis and trial sampling into early-to-mid commercial deployment. Once viewed primarily through the lens of theoretical academic research, graphene—a single-atom-thick layer of carbon arranged in a two-dimensional hexagonal lattice—is increasingly integrated into revenue-generating industrial supply chains. Current commercial demand is centered around performance-enhancing masterbatches for polymer composites, energy storage additives in lithium-ion and next-generation battery chemistries, thermal management interfaces for electronics, concrete and asphalt reinforcement, and specialized biosensors.
For public market investors, assessing graphene stocks requires understanding how equity exposure is distributed across global capital markets. The commercial landscape is divided into two distinct groups:
- Venture and Secondary Exchanges: Pure-play graphene synthesis and functionalization firms are predominantly listed on small-cap and venture exchanges, including the Toronto Stock Exchange (TSX and TSX-V), the London Alternative Investment Market (AIM), the Australian Securities Exchange (ASX), and Over-the-Counter markets (OTCQX and OTCQB) in the United States.
- Major Global Indices: Large-cap industrial chemical conglomerates, carbon black producers, and semiconductor capital equipment manufacturers trade on major exchanges such as the New York Stock Exchange (NYSE) and NASDAQ. For these companies, graphene represents an incremental growth product line or an equipment enablement vertical rather than their primary revenue driver.
Pure-Play Producers vs. Diversified Conglomerates
Investors analyzing the advanced materials sector must distinguish between pure-play producers and diversified legacy corporations. Each structure presents fundamentally different risk-reward profiles, operational leverage characteristics, and capital intensity requirements.
| Category | Business Model & Revenue Focus | Operational Profile | Investment Profile |
|---|---|---|---|
| Pure-Play Nanomaterial Producers | Revenues are tied directly to proprietary graphene powder synthesis, chemical functionalization, masterbatch compounding, and intellectual property licensing. | Agile R&D teams, dedicated manufacturing facilities (measured in tens to thousands of tonnes per year), custom client co-development pipelines. | High operational leverage to commercial adoption; higher volatility, micro-to-small market capitalization, and exposure to equity dilution risk during scale-up phases. |
| Diversified Industrials & Equipment Enablers | Graphene represents an additive product line, advanced carbon R&D division, or deposition hardware segment alongside established core industrial businesses. | Multi-billion-dollar global distribution networks, legacy chemical production assets, extensive patent defense budgets. | Strong cash flow generation from mature businesses, lower sensitivity to graphene-specific adoption delays, but limited top-line sensitivity to broad graphene market growth. |
Notable Public Graphene Companies
The following curated list outlines prominent publicly traded companies active in the synthesis, functionalization, compounding, and equipment enablement of graphene and related two-dimensional nanomaterials.
1. NanoXplore Inc.
- Primary Ticker & Exchange: TSX: GRA (Toronto Stock Exchange)
- Secondary / US Ticker: OTCQX: NNXPF
- Business Classification: Pure-Play Producer & Industrial Compounder
- Core Focus & Applications: Headquartered in Montreal, Canada, NanoXplore is one of the largest global producers of industrial-scale graphene powder under the trade name GrapheneBlack™. The company specializes in integrating graphene into standard thermoplastic polymers, automotive lightweighting components, packaging materials, and developing silicon-graphene composite formulations for electric vehicle battery anodes.
2. Directa Plus plc
- Primary Ticker & Exchange: AIM: DCTA (London Stock Exchange)
- Secondary / US Ticker: OTC: DTPKF
- Business Classification: Pure-Play Advanced Materials Producer
- Core Focus & Applications: Directa Plus utilizes a proprietary, chemical-free thermal exfoliation process to produce pristine graphene nanoplatelets marketed as G+®. Key operational divisions focus on environmental remediation (using its Grafysorber® technology for hydrocarbon and oil-spill absorption), high-performance technical textiles, elastomeric compounds for footwear, and asphalt additives designed to increase road longevity.
3. Haydale plc
- Primary Ticker & Exchange: AIM: HAYD (London Stock Exchange)
- Secondary / US Ticker: OTC: HDGHF
- Business Classification: Advanced Materials & Functionalization Specialist
- Core Focus & Applications: Formerly known as Haydale Graphene Industries, the UK-based company centers its value proposition on its proprietary HDPlas® low-temperature plasma functionalization process. This clean technology modifies the surface chemistry of graphene and other nanomaterials to resolve industrial dispersion bottlenecks. Commercial targets include conductive inks, thermal underfloor heating elements, composite tooling, and specialized thermal management solutions for data centers.
4. First Graphene Ltd.
- Primary Ticker & Exchange: ASX: FGR (Australian Securities Exchange)
- Secondary / US Ticker: OTCQB: FGPHF
- Business Classification: Pure-Play Producer & Solutions Provider
- Core Focus & Applications: Operating an automated manufacturing facility in Henderson, Western Australia, First Graphene manufactures high-purity graphene additives marketed under the PureGRAPH® brand. The company targets bulk industrial adoption, with a strong focus on cement and concrete additives (to reduce clinker content and associated carbon emissions), wear-resistant elastomer liners for the mining sector, and structural fire-retardant composites.
5. CVD Equipment Corporation
- Primary Ticker & Exchange: NASDAQ: CVV
- Secondary / US Ticker: N/A
- Business Classification: Capital Equipment & Deposition Enabler
- Core Focus & Applications: Rather than producing raw materials, CVD Equipment designs and manufactures chemical vapor deposition (CVD), physical vapor transport (PVT), and specialized gas control systems. Its manufacturing and laboratory equipment platforms are deployed by institutional researchers and commercial manufacturers to synthesize 2D materials (such as graphene and transition metal dichalcogenides), carbon nanotubes (CNTs), and silicon carbide (SiC) power semiconductors.
6. Archer Materials Ltd.
- Primary Ticker & Exchange: ASX: AXE (Australian Securities Exchange)
- Secondary / US Ticker: OTC: ARRXF
- Business Classification: Deep-Tech & Semiconductor Device Developer
- Core Focus & Applications: Archer Materials is a fabless deep-technology company developing advanced semiconductor chips and biosensing devices. Its primary graphene initiative is the A1 biochip, which integrates graphene-based field-effect transistors (gFETs) to enable multi-disease diagnostic testing on a single lab-on-a-chip platform.
7. Cabot Corporation
- Primary Ticker & Exchange: NYSE: CBT
- Secondary / US Ticker: N/A
- Business Classification: Diversified Specialty Chemicals Conglomerate
- Core Focus & Applications: Cabot is a major global producer of specialty carbon black and rubber reinforcements. Through internal development and historical acquisitions, Cabot has expanded its advanced carbon portfolio to include graphene nanoplatelets (such as its PBX® series) and carbon nanostructures tailored for lithium-ion battery electrode conductivity, energy storage applications, and functional plastics.
Key Investment Risks in Advanced Materials Equities
Investing in early-stage and specialty material equities involves structural risks that differ markedly from software, biotech, or mature consumer manufacturing. Key operational and market risks specific to graphene companies include:
Extended Qualification and Testing Cycles
Integrating a novel nanomaterial into safety-critical or heavily regulated industries—such as automotive chassis, commercial aerospace components, or infrastructural concrete—requires multi-year validation phases. End-users must test materials for long-term fatigue, environmental degradation, and regulatory compliance (such as REACH registration in Europe or TSCA compliance in the United States). These extended qualification timelines frequently delay anticipated revenue scale-ups.
Manufacturing Scale-Up and Dispersion Bottlenecks
Demonstrating enhanced mechanical or electrical properties in a laboratory setting does not guarantee cost-effective mass production. Graphene sheets naturally tend to agglomerate due to strong van der Waals forces, which can neutralize their specialized properties if improperly mixed into a host matrix. Companies must scale synthesis while maintaining batch-to-batch quality consistency and delivering effective, proprietary dispersion methods.
Cash Burn and Negative Operating Margins
Many pure-play graphene firms operate at negative EBITDA margins, spending capital on continuous research, pilot trials, and client co-development programs before securing high-volume commercial off-take contracts. Extended development phases can lead to sustained cash burn.
Shareholder Dilution via Secondary Offerings
Because pure-play micro-caps often lack self-funding operating cash flows during the early commercialization phase, capital expenditure for commercial expansion is frequently financed through equity private placements, warrant issuances, or convertible debt notes. These transactions can dilute existing common equity holdings.
Direct Competition from Incumbent Industrial Additives
Graphene does not operate in a vacuum; it competes against established, low-cost industrial additives such as carbon black, milled carbon fiber, synthetic graphite powders, and precipitated silica. For mass-market adoption, graphene producers must demonstrate not only technical superiority but also clear cost-in-use advantages over incumbent supply chains.
Evaluating Graphene Equities: A Fundamental Framework
When performing due diligence on advanced materials companies, institutional and private investors typically assess several underlying operational and financial factors rather than relying on non-binding press releases:
- Quality and Source of Revenue: Assess the ratio of commercial product shipments and compounding revenues relative to one-off government grants, research subsidies, or legacy consulting arrangements.
- Binding Off-Take Agreements vs. MOUs: Differentiate between legally binding supply contracts with Tier-1 industrial partners and preliminary, non-binding Memorandums of Understanding (MOUs) or testing joint development initiatives.
- Nameplate Capacity vs. Utilized Throughput: Scrutinize announced manufacturing capacity (expressed in metric tonnes per year) against actual operating yields and verified shipment volumes.
- Functionalization and Processing IP: Evaluate the breadth and defensibility of the company’s patent portfolio, focusing on chemical or mechanical functionalization techniques that solve the industrial dispersion challenge.
- Balance Sheet Health and Cash Runway: Measure net working capital, total long-term debt obligations, and remaining operational cash runway (in months) relative to trailing quarterly burn rates.
Thematic Baskets and Venture Capital Trends
Direct exposure to graphene through public markets remains concentrated in a small group of listed companies. Investors seeking broad exposure to advanced carbon materials often review diversified thematic strategies, such as materials science or clean technology exchange-traded funds (ETFs). However, because graphene remains a niche sub-segment within the broader $1-trillion-plus specialty chemicals and industrial sectors, dedicated pure-play graphene ETFs do not currently exist on major exchanges.
Concurrently, significant commercial development occurs within privately held, venture-backed startups focused on next-generation synthesis techniques (such as flash Joule heating or biowaste conversion), CVD graphene for photonics, and specialized membrane filtration. Tracking early-stage venture rounds and corporate venture capital (CVC) investments from industrial chemical leaders provides insight into the commercial applications most likely to enter the public equity markets in future initial public offerings.
Comprehensive Investment Disclaimer
The information provided in this research overview is for institutional and retail educational purposes only and does not constitute a solicitation, recommendation, endorsement, or financial offer to purchase or sell any equity, bond, derivative, or alternative financial instrument. The equities discussed operate within speculative, highly volatile advanced material sectors characterized by capital expenditure requirements, regulatory hurdles, and potential total loss of invested capital. Past performance of any company, index, or sector is not indicative of future returns. Readers must perform independent financial, legal, and operational due diligence and consult with an accredited, licensed investment advisor or registered broker-dealer before committing capital to any public or private financial asset.